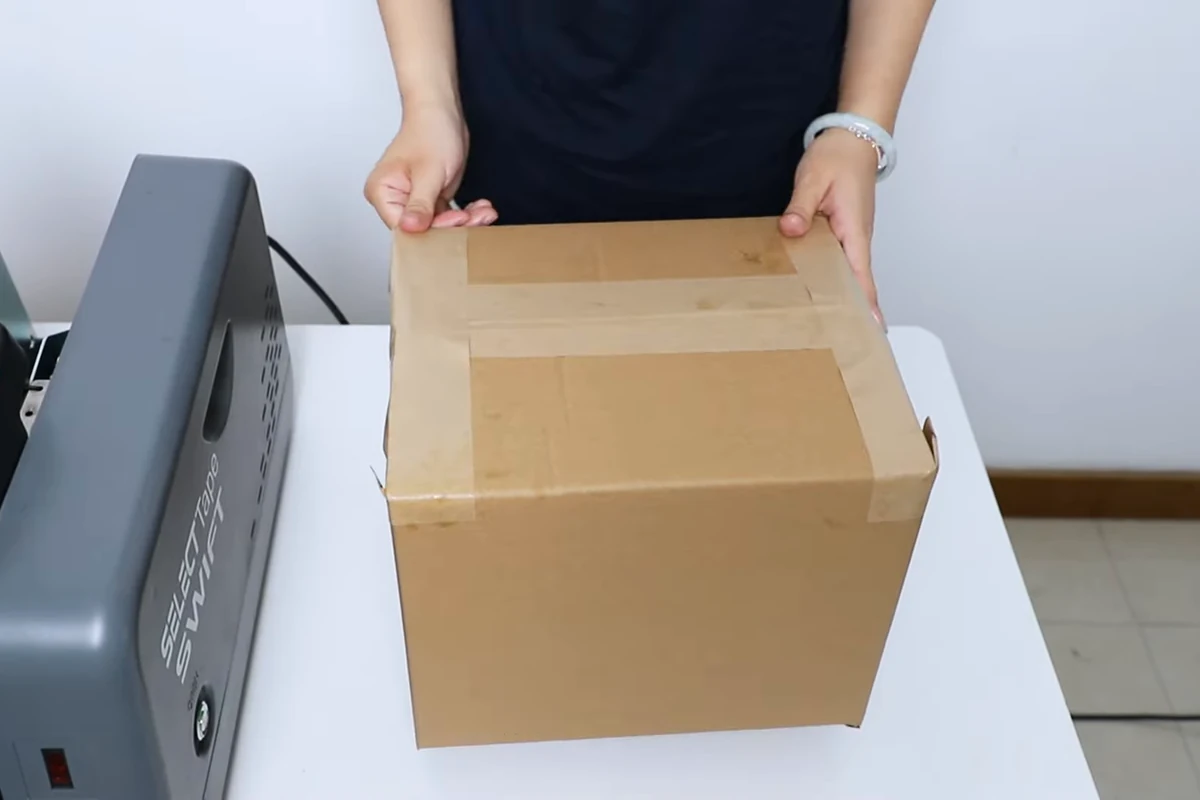
Calculate water-activated tape cost per carton by dividing the cost of tape actually consumed during a measured period by the number of accepted cartons from that period. For a fuller station comparison, add attributable labor and operating costs, then show equipment allocation separately.
Use accepted cartons as the denominator, include tape lost in discarded strips or failed closures, and count rework once. Roll price alone does not describe carton-sealing cost, and a hypothetical calculation does not establish savings for a real operation.
Set the measurement boundary first
A useful cost record defines the carton task, time period and acceptance criteria before collecting numbers. Costs and carton count must cover the same work.
State whether the station seals only the top of a preclosed carton or both top and bottom. Record the required closure pattern, carton families and tape grade. If the comparison uses a different seam pattern, the two figures describe different tasks rather than competing costs for the same closure.
Choose a period that captures the normal carton mix, replenishment and recurring interruptions. Count each accepted carton once, including a carton accepted after rework. Rejected cartons consume material and labor but do not enter the accepted-carton denominator until they pass within the measured period.
For a short trial, start and finish with no partly sealed or unreleased cartons. If unfinished work crosses the period boundary, reconcile its attributable tape and labor with the same batch of completed cartons before comparing costs. Distinguish confirmed scrap from costs carried with unfinished work; tape already applied to an unfinished carton is not reusable roll inventory.
For mixed cartons, either report each family separately or state the mixture clearly. A change from large boxes to small ones can reduce the average tape figure even when the station itself has not improved.
Convert the roll price to a comparable length cost
Cost per metre equals the landed cost of the roll divided by its usable feedable length. Use the same length basis for every candidate and identify any fixed unusable portion included in that basis.
Tape cost per metre = landed roll cost ÷ usable feedable metres per roll
Landed cost should include the purchase and delivery costs your business assigns to that consumable. Use the currency and tax treatment agreed by finance. Do not compare one delivered price with another ex-works price without accounting for the difference.
For usable length, confirm the supplier’s declared length, tolerances and roll construction. If a fixed end portion cannot be dispensed and is excluded from usable length, its purchase cost is already distributed across the remaining usable metres. Do not charge that same fixed portion again as variable strip scrap.
Before selecting a longer roll solely for its unit price, check dispenser compatibility, including full-roll diameter and core format. An unusable bulk order is not a lower-cost consumable.
Measure consumed tape, including unsuccessful work
Actual tape consumption includes the usable tape removed from inventory for the measured task, whether it ends on an accepted carton or becomes scrap. Partly used rolls that remain available for later work are closing inventory, not fully consumed rolls.
One inventory method is:
Consumed usable metres = opening usable inventory + usable metres issued − closing usable inventory − usable metres returned elsewhere
Keep opening, issued and closing quantities within the same station boundary. Count a roll in either closing inventory or a reusable return, never both. Tape discarded during the period is no longer reusable inventory and is therefore included in consumption.
Directly measuring total dispensed length is another method when the record is reliable. Include rejected and repeated strips, and reconcile that measurement with inventory where practical. Do not add a blanket waste percentage to a measurement that already includes waste.
Tape cost per accepted carton = consumed usable metres × cost per metre ÷ accepted cartons
The formula applies directly to a completed batch or a period with no opening or closing unfinished work. If work crosses the boundary, add tape costs carried in with opening unfinished work and subtract tape costs carried out with closing unfinished work before dividing by accepted cartons. Keep the physical consumption record separate from this cost-allocation adjustment, and apply the same completed-work boundary to labor.
For planning before a trial, theoretical tape length is the sum of all required strip lengths per carton. Label that result as planned consumption. Add measured loss separately only when loss is not already included. Keep the trial’s actual consumption distinct from the planning estimate.
Add labor using person-hours
Labor cost uses the total worker time attributable to the sealing task, multiplied by the applicable hourly labor cost. Two workers occupied for one hour contribute two person-hours.
Attributed labor cost = attributable person-hours × applicable cost per person-hour
State whether the rate includes employer costs or only wages. Use the same basis for alternative workflows. When operators perform other tasks at a shared bench, measure or allocate the sealing portion transparently rather than charging the whole shift to tape.
Include recurring loading, water replenishment, approved routine care and closure rework within the chosen labor boundary. If the measured person-hours already include rework, do not add a second “rework labor” allowance. Record unusual setup or training separately when it is not part of steady operation.
Identify other attributable operating items, such as measured consumables, utilities or service cost, only when their amounts and allocation are defensible. Avoid estimating a detailed decimal result from guessed inputs.
A worked example with hypothetical inputs
The following example illustrates the calculation only. These are invented planning inputs, not SelectPack prices, production measurements or a savings claim.
Assume the measured period starts and ends with no unfinished sealing work and produces 1,000 accepted cartons. Each accepted carton uses three 0.40 m strips, so the accepted closures contain 1,200 m of tape. A further 300 m of usable tape is consumed in discarded strips and unsuccessful or repeated work, giving 1,500 m of total consumed tape.
Assume the landed tape cost is USD 20 per roll with 200 usable feedable metres. Attributable labor totals six person-hours at USD 20 per person-hour. Other measured operating items total USD 10. A separately chosen equipment allocation for the period is USD 20.
| Calculation | Result |
|---|---|
| Tape cost per metre: 20 ÷ 200 | USD 0.10/m |
| Consumed tape cost: 1,500 × 0.10 | USD 150 |
| Tape cost per accepted carton: 150 ÷ 1,000 | USD 0.15 |
| Labor: 6 × 20 | USD 120 |
| Operating total: 150 + 120 + 10 | USD 280 |
| Operating cost per accepted carton: 280 ÷ 1,000 | USD 0.28 |
| Total with equipment allocation: (280 + 20) ÷ 1,000 | USD 0.30 |
The 300 m loss is already included in the USD 150 tape total. Adding it again as a separate scrap charge would overstate cost. The six person-hours include the repeated work, so no second rework-labor charge is added either.
In a separate planning scenario, suppose loss falls from 300 m to 150 m while accepted carton count, closure length and every other input stay unchanged. Consumed tape becomes 1,350 m, tape cost becomes USD 135, and tape cost per accepted carton becomes USD 0.135. That arithmetic isolates one variable; it is not evidence that a new machine will achieve the reduction or leave labor unchanged.
Keep equipment allocation separate from cash operating cost
Equipment allocation depends on the accounting method, purchase cost and expected use selected by the business. Show the method rather than burying an arbitrary machine charge inside tape cost.
State whether the figure represents depreciation, a lease charge or another approved allocation. If equipment supports several stations or tasks, disclose the usage basis. A period’s allocated expense is different from the initial purchase cash outflow; do not combine both as if they were separate costs of the same period.
Payback needs a verified difference in future operating cash costs, with implementation and service assumptions. This per-carton worksheet supplies inputs for that decision but does not establish return on investment by itself.
Use the calculation to find the next investigation
Separate material price, closure length, loss and labor so a cost change has an identifiable cause. If tape consumption rises, check the carton mix and closure pattern before blaming the roll price. If person-hours rise, examine repeated handling and rework rather than assuming faster dispensing would solve the station bottleneck.
For an alternative material route, use the water-activated versus pressure-sensitive tape workflow comparison and retain the same cost boundaries. Both candidates must meet the package requirement before their costs are treated as comparable.
Send SelectPack the tape grade, roll specification, carton mix, closure lengths, consumed quantity and accepted carton count when requesting a tape-and-dispenser quotation. Those inputs allow a quote to be placed into your calculation, with unmeasured operating results left for a station trial.